01
Open the account needing attention
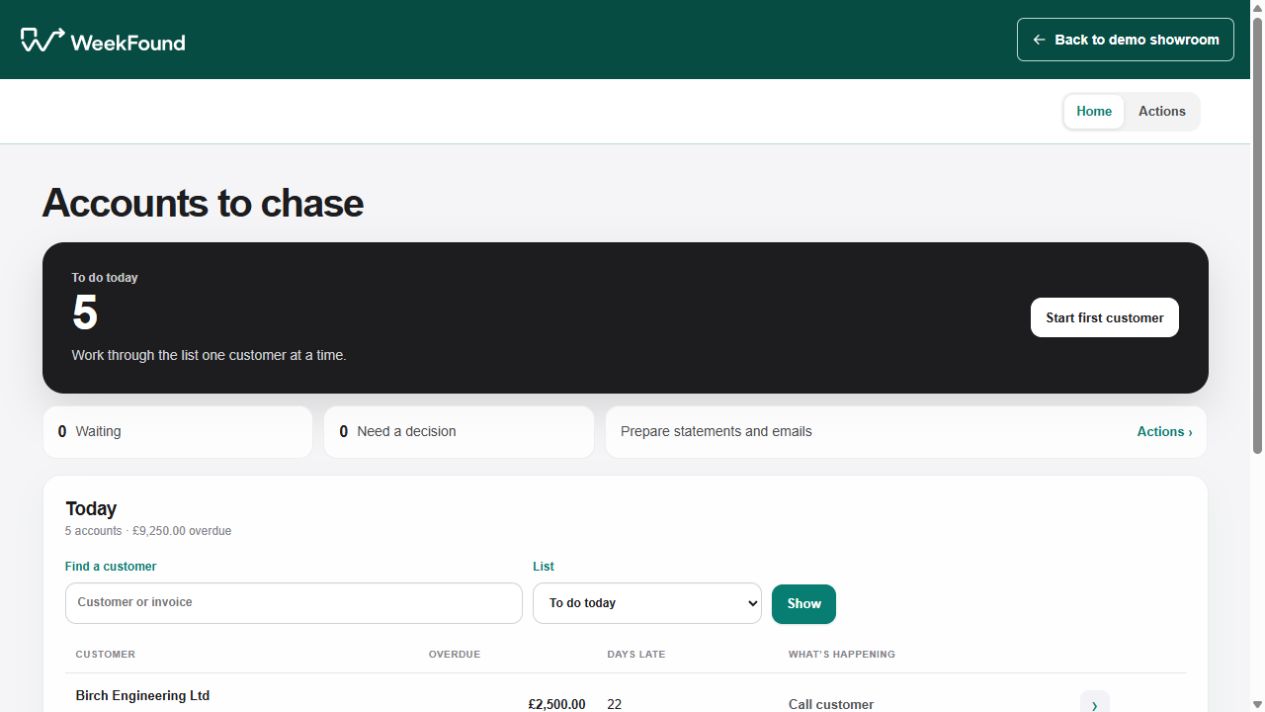
Start from the overdue account queue and inspect the balance and relevant invoices.

Finance and customer accounts · Showroom demonstration
An overdue date tells the team that an invoice needs attention. It does not explain whether the customer has asked for a copy, disputed the amount or promised a payment. Finding that context can take longer than writing the next email.
Who this is for: Finance and credit-control teams handling overdue invoices, account queries and payment promises.
Credit control
This credit-control demonstration brings the account balance, invoices and latest contact together. The collector can select customers and review an editable message for each one before confirming a simulated send, without treating the email as evidence that the debt has been paid.
In the fictional account, Alder Workshop has an overdue balance and an invoice-copy request. The collector reads the contact and invoice details, selects the relevant customer and opens the email review box. Each selected customer has its own recipient, subject and editable message.
The person can cancel or confirm the simulated send after checking the emails. The outstanding balances remain intact: sending a collection email does not clear an invoice. That distinction also matters when a customer says it has paid but the team still needs to check the accounting evidence.
From the repeated task to a reviewable result
01
Start from the overdue account queue and inspect the balance and relevant invoices.
02
Check the invoice-copy request alongside the account details before choosing the follow-up.
03
Select one or more customers, open Email and check each recipient, subject and editable message in the review box.
04
Confirm the simulated send only after reviewing the messages. The action remains private and does not clear any outstanding invoice.
Practical answers
Bring together current invoice balances, recent payment information, customer replies and any dispute status before deciding what may be sent. The demonstration shows the account review. A live sending workflow would require agreed rules, verified recipients and a final current-state check.
Treat the request as work to resolve, not as a reason to send a more forceful reminder. The demo puts the request alongside the invoices so the collector can review the relevant document and prepared wording. Its document and email actions are simulated.
No. A message is evidence of what the customer has said, not proof that the balance has been cleared. Check the authorised payment and accounting records, resolve any matching issue, and keep the balance open until the agreed accounting evidence supports a change.
Yes. Select the relevant customers and open the email review box. Each customer has a separate recipient, subject and editable message, and you can cancel rather than confirm the send. Sending is simulated in this demo; no real customer receives an email.
Keep them visible with the account and let them change the next action. A dispute may need investigation, while a promise needs an agreed date and subsequent payment check. Decisions about arrangements, concessions or escalation remain with the responsible person.
Credit control starts with the account balance and the invoices requiring attention. Email management starts with an incoming message and prepares an appropriate response or action. They can support the same finance process, but they answer different day-to-day questions.
Measure preparation and review time, missed follow-ups, messages sent after payment, unresolved queries and corrections. Track cash collected separately using actual account evidence. More messages are not automatically a better collections result, and the fictional demo does not establish a collection increase.
Your business and existing tools
We would first review the account data and the reasons reminders currently go wrong. The invoice chasing guide explains payment, reply and dispute checks. The AI finance agent case study describes related completed finance work separately from this fictional demo, and services and pricing sets out the service offer.
WeekFound starts by looking at the repeated work, the time the team spends on it and the mistakes that need correcting. The aim is to give the existing team more capacity as the business grows.
Collectors own disputes, negotiations, payment arrangements and escalation. A prepared reply or payment promise does not authorise an accounting change.
Count account-review minutes and the work involved in finding invoices and conversation history. Include correction and approval time. Keep any cash-recovery measure tied to the actual customer records and period.
Start with one useful piece of work
Tell us how the task works today, where it gets stuck and what a correct result needs to look like. We can then assess the work, the source data and the review points before agreeing a suitable approach. Essential work should retain a usable manual fallback if an automation or source system changes.
Discuss this workflow